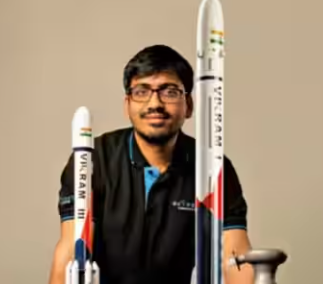
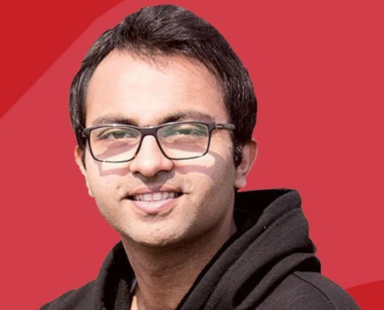
Shashank Kumar grew up in a farming family in Chhapra, Bihar, watching a particular kind of arithmetic repeat every season. The family grew the crop, took the risk, absorbed the weather — and then watched a disproportionate share of the money go to brokers and middlemen between the field and the market.
He got out the way bright Bihari students do: IIT Delhi, graduating in 2008, then a corporate career including Unilever and consulting. Then, three years in, he went back.
Fifty farmers in Vaishali
In 2012 Kumar and Amrendra Singh began working with about fifty farmers in Vaishali district, testing a simple proposition: that the crisis in Indian agriculture was less about farming technique than about broken supply chains and missing information.
They were joined by Shyam Sundar Singh, Adarsh Srivastava and Abhishek Dokania, and named the company DeHaat — Hindi for village.
Bihar was not where Indian startups were being built in 2012. That was exactly the point. There was no established playbook for rural agritech, which meant no incumbent to displace and no competitor bidding up the cost of each farmer relationship.
The full-stack bet
Most agritech startups pick one slice: an app for advice, a marketplace for produce, a lender for working capital. DeHaat’s thesis was that no single slice works, because a farmer who gets good advice but cannot buy quality seed, or sells well but cannot access credit, is still stuck.
So DeHaat built the whole chain: agricultural inputs, expert advisory, credit facilitation, and market linkage to institutional buyers — delivered not through an app alone but through a network of local micro-entrepreneurs running physical DeHaat centres in their own villages.
That hybrid of digital and physical is the expensive, slow, defensible part. A competitor can clone the app in a quarter. Eighteen thousand village centres take a decade.
Where it stands
DeHaat now reaches millions of farmers across more than ten Indian states and over a lakh villages. It crossed ₹3,000 crore in revenue in FY25, making it India’s largest full-stack agritech company by revenue, and Kumar has said it is running at an annual revenue run rate of around ₹4,000 crore.
It has raised over $250 million from investors including Temasek, Sofina, Peak XV, Prosus and Lightrock, and in January 2026 raised roughly ₹725 crore in a Series D led by GEF Capital Partners — one of the largest agritech rounds of the year. The company turned profitable in Q1 FY26 and is targeting full-year profitability.
On an IPO, Kumar has been unusually restrained: no plans for the next two years, and a listing only after sizeable profitability.
The context that makes it harder
Indian agritech funding fell from over $360 million in 2024 to roughly $160 million in 2025. Capital for the sector has largely dried up, which means the companies still standing are those that built real revenue rather than farmer sign-up counts.
What founders should take from it
The hardest market to enter is often the least contested. Rural Bihar had no playbook, no investors watching, and no competitors. That is a cost and a gift.
Partial solutions fail in broken systems. Where every link in the chain is weak, fixing one link just moves the bottleneck.
Physical networks are slow moats, which is why they last. Anything you can build in a quarter, someone else can too.
A farmer’s son left for IIT Delhi, took the corporate job his family would have wanted, and then went back to the problem he had grown up inside. Fifty farmers became millions.